Marico Ltd. – Leading Consumer Wellness Brand
Marico Limited, incorporated in 1988 and headquartered in Mumbai, Maharashtra, is one of India’s leading consumer products companies operating in the beauty and wellness categories. The company ranks first in each of its five key reported franchises, including a 59% volume share in Parachute rigids within coconut oil and a 29% value share in value-added hair oils (MAT June 2026). It reports two segments, India and International, which contributed 76% and 24% of Q1FY27 revenue respectively; the international business spans Bangladesh, Vietnam, MENA and South Africa, with markets outside Bangladesh forming 59% of international revenue. The company operates through a robust manufacturing infrastructure comprising 6 domestic and 8 international facilities, catering to diverse consumer needs.
Products and Services
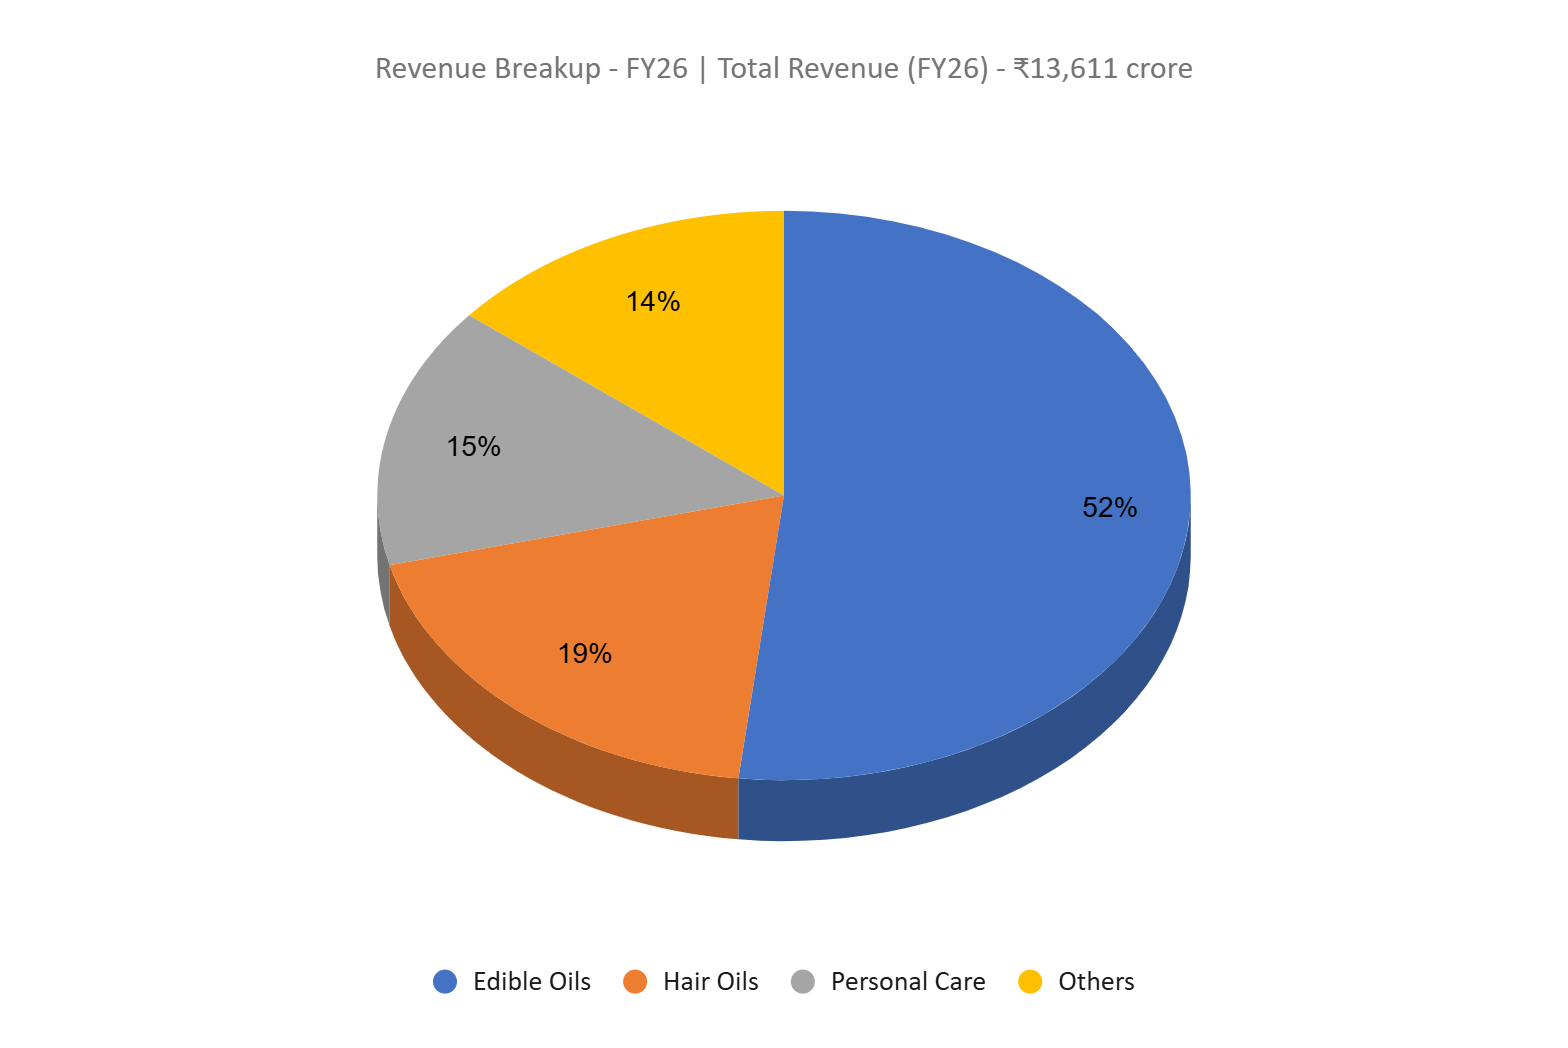
Marico sells branded consumer products in India and overseas, with coconut oil at the core. The India portfolio has three parts:
- Parachute coconut oil, Saffola edible oils and value-added hair oils such as Parachute Advanced and Nihar Naturals.
- Foods, led by Saffola Oats and muesli.
- Premium personal care and digital-first brands, including Beardo, Plix, Just Herbs, Cosmix and 4700BC.
Subsidiaries: As of FY26, the company has 22 subsidiaries and no other joint ventures/associate companies.
Investment Rationale
- Resilient core business with volume-led growth and margin recovery – Marico’s core business continues to demonstrate resilience, with underlying volume growth remaining strong despite price hikes taken to offset elevated input costs. In Q1FY27, the India business recorded 11% volume growth, led by 10% volume growth in Parachute and 22% value growth in value-added hair oils (VAHO), supported by premium products and market share gains. In Q2FY27, Parachute volumes accelerated to early-teens growth, while VAHO sustained growth of over 20%, reflecting healthy demand across key franchises. Saffola delivered mid-single-digit price-led growth, although volumes remained subdued as the company prioritised profitability amid input cost pressures. Meanwhile, the company’s distribution initiatives under Project SETU, expansion in the almond oil category and strong quick-commerce performance are supporting market penetration. With copra prices remaining below their previous peak, the company expects improvement in gross margins, supported by favourable portfolio mix and lower input costs. Management has reiterated its focus on volume-led growth and expects to surpass its near-term guidance following strong H1 performance, while retaining its FY30 revenue target of ₹20,000 crore.
- Scaling digital-first brands and premium food businesses to drive incremental growth – Marico is expanding beyond its established hair care and edible oil franchises by scaling digital-first brands and premium food businesses, creating additional avenues for long-term growth. Its digital portfolio, led by Beardo and Plix, has crossed an annual recurring revenue (ARR) of ₹1,100 crore, with the businesses demonstrating improving operating profitability. Plix has grown sixfold in two years, with EBITDA margins improving by 1,100 basis points between FY24 and FY26. Marico has further strengthened its position in the brand by increasing its stake in Satiya Nutraceuticals, the parent company of Plix, from 60% to 84.09% through the acquisition of an additional 24.09% stake. Management expects Plix to achieve double-digit EBITDA margins in the near term. The company has also expanded its portfolio through the acquisitions of 4700BC, a premium snacking brand, and Cosmix, which focuses on vegan and gut-friendly nutrition. 4700BC has achieved an ARR of ₹140 crore, while Cosmix has reached ₹100 crore, with management targeting 3.5x and 3x growth, respectively, by FY30. These businesses provide additional growth engines beyond Marico’s core categories, while improving profitability and operating leverage could support incremental earnings growth over the medium term. In April 2026, it acquired a 75% stake in Vietnam-based Skinetiq, which owns the skincare brand Candid and holds exclusive Vietnam distribution rights for Murad.
- Q1FY27 – On a consolidated basis, Marico reported revenue from operations of ₹3,957 crore in Q1FY27, up 22.9% YoY from a restated ₹3,221 crore in Q1FY26 and 19.9% QoQ, with the quarter including Skinetiq from April 2, 2026. India revenue rose 20.9% YoY to ₹3,003 crore on 11% underlying volume growth, its highest in 20 quarters, led by 10% volume growth in Parachute rigids, 22% value growth in value-added hair oils and 43% growth in foods, while International revenue grew 29.3% to ₹954 crore (15% constant currency growth), led by Vietnam (27% CCG) and MENA (24% CCG). Gross margin improved ~30 bps YoY on softer copra prices and a favourable mix, and despite a 25% rise in A&P spend to ₹327 crore, EBITDA rose 25.0% to ₹819 crore, with margin expanding ~40 bps to 20.7%. PBT grew a slower 20.4% to ₹790 crore on higher depreciation and finance costs and lower other income, but a lower effective tax rate of 17.5% (versus 21.8%), aided by a deferred tax credit of ₹62 crore, lifted net profit 25.0% to ₹630 crore.
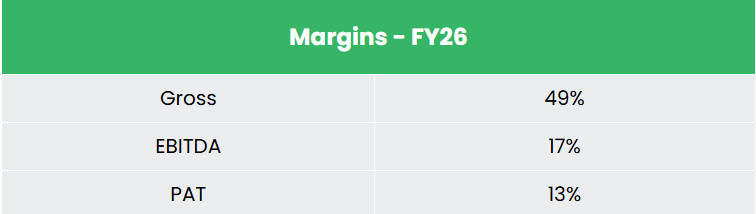
- FY26 – During FY26, Marico reported consolidated revenue from operations of ₹13,611 crore, up 25.7% YoY from ₹10,831 crore in FY25 and its highest growth in 14 years, driven by 8% underlying volume growth in India (a seven-year high) and 20% constant currency growth in the International business (a 14-year high); after the Q1FY27 reclassification of customer-related promotional spends against revenue, FY26 revenue stands restated at ₹13,478 crore, with no impact on profit. EBITDA rose 8.8% to ₹2,328 crore, while EBITDA margin contracted ~265 bps to 17.1% (from 19.7%) as elevated copra prices pressured gross margins. Net profit attributable to owners rose 8.2% to ₹1,762 crore (from ₹1,629 crore), or 11% excluding one-offs.
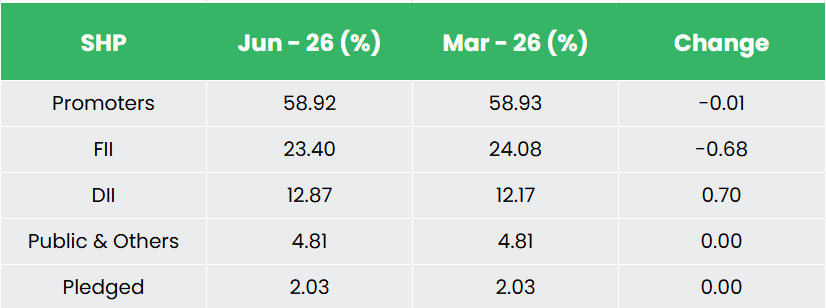
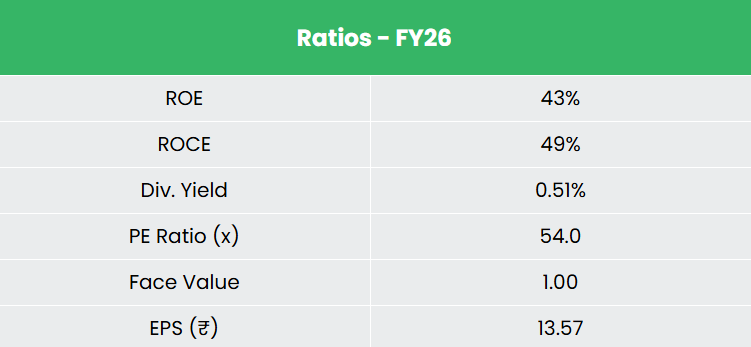
- Financial Performance – The 3-year revenue and net-profit CAGR stand at around 12% and 11% respectively (FY23–FY26). The company has returned a 3-year average ROE and ROCE of around 43% and 47% respectively, with a debt-to-equity ratio of 0.13x as of March 2026. Operating cash flow of ₹2,084 crore in FY26 (~90% of EBITDA) translated into free cash flow of ₹1,772 crore, and net working capital days improved to 26 in Q1FY27 from 34 in Q4FY26.
Industry
India’s FMCG sector generated is projected to grow at a CAGR of 17.33% to nearly US$ 642.87 billion by FY30. Household and personal care, the segment that houses Marico’s hair care and personal care franchises, accounts for ~50% of the FMCG market. Demand momentum improved through FY26, with NielsenIQ reporting Q2FY26 value growth of 12.9% and volume growth of 5.4%, supported by a 7.7% rise in rural volumes, while sector revenue growth rose to 7.5% in Q3FY26 from 2% in the previous quarter. Urban markets accounted for around 62% of FMCG revenue in 2025, with rural India contributing over 38%, and urban volume growth of 4.6% in 2025 overtook rural growth of 3.6%. Within personal care, India’s beauty and personal care market is projected to nearly double to ~US$ 40 billion by 2030, driven by Gen Z-led demand, digital adoption and the rapid rise of quick commerce.
Growth Drivers
- Quick commerce and digital channels: Quick commerce is scaling rapidly, with GMV and users growing 100%+ YoY across over 5,000 dark stores, and FMCG companies recorded 50–100% YoY sales growth on quick commerce platforms in FY25. Beauty and personal care, with ~20% online penetration and ~26% growth in Tier 2+ markets, is among the fastest-digitising categories, a trend that favours Marico, whose quick commerce sales grew over 50% in Q1FY27 and whose digital-first personal care portfolio reached an annualised revenue run-rate of ₹1,100+ crore.
- Premiumisation reaching rural India: In 2025, rural India accounted for a 51% volume share of affordable premium FMCG and 42% of super-premium sales, as average rural premium spend grew at an 11% CAGR over five years into a ₹98,000 crore (US$ 11.38 billion) market. This supports Marico’s shift towards premium and digital portfolios, which it expects to rise to 44% of revenue in FY27 from 37% in FY26, while Project SETU targets 1.5x direct reach by FY27 versus FY24, including pan-India rural expansion.
- Consolidation in D2C and healthy foods: India’s D2C market crossed ₹6,96,400 crore (US$ 80 billion) in 2024, and around two-thirds of acquisitions by FMCG firms between FY21 and FY25 were in the D2C space, per Crisil Ratings, while the healthy snack market, valued at US$ 3.13 billion in 2025, is expected to reach US$ 4.77 billion by 2034. Marico has been an active consolidator, acquiring Beardo, Plix, Just Herbs, True Elements and 4700BC, and its foods portfolio grew 43% in Q1FY27 to an annualised revenue run-rate of ₹1,300+ crore.
Peer Analysis
Competitors: Dabur India Ltd, Emami Ltd, etc.
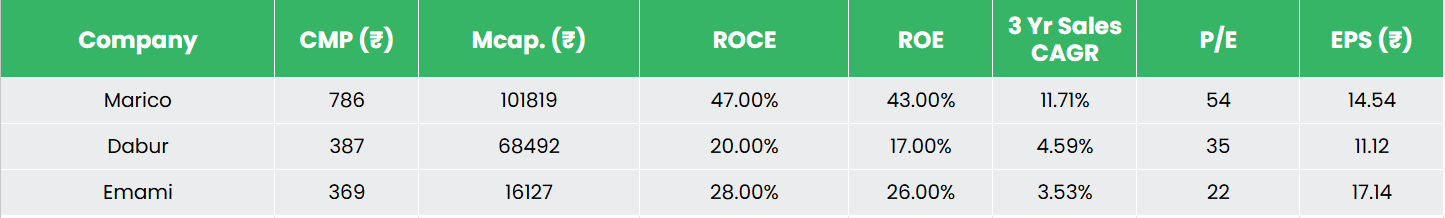
Marico is the highest-returning and fastest-growing company in the set, with ROCE and ROE of 47% and 43%, against 21% and 18% at Dabur and 31% and 29% at Emami, both of which also compete in hair oils. Its 3-year sales CAGR of 12% is more than twice that of Dabur and Emami, driven by volume-led growth in its core franchises alongside the scale-up of foods and digital-first brands. Marico’s superior growth and return profile is reflected in its P/E premium to both peers.
Outlook
Marico is well-positioned to sustain profitable growth, supported by resilient demand across its core franchises, improving product mix and expansion into high-growth consumer categories. The company has demonstrated its ability to pass on elevated input costs through calibrated price hikes while maintaining volume growth, with underlying India volume growth reaching double digits in both Q1FY27 and Q2FY27. With copra prices remaining around 35% below their peak, the company expects a steady year-on-year improvement in gross margins, providing scope for earnings growth alongside continued volume expansion. Its premium value-added hair oils, digital-first brands and food businesses are gaining traction, while international operations provide additional growth opportunities. Marico is targeting revenue of over ₹15,000 crore and high-teen EBITDA growth in FY27, with a longer-term ambition of reaching ₹20,000 crore in revenue by FY30. The continued scaling of acquired brands, alongside improving profitability and a shift towards premium and higher-margin categories, could support sustained revenue growth and operating leverage over the medium term.
Valuations
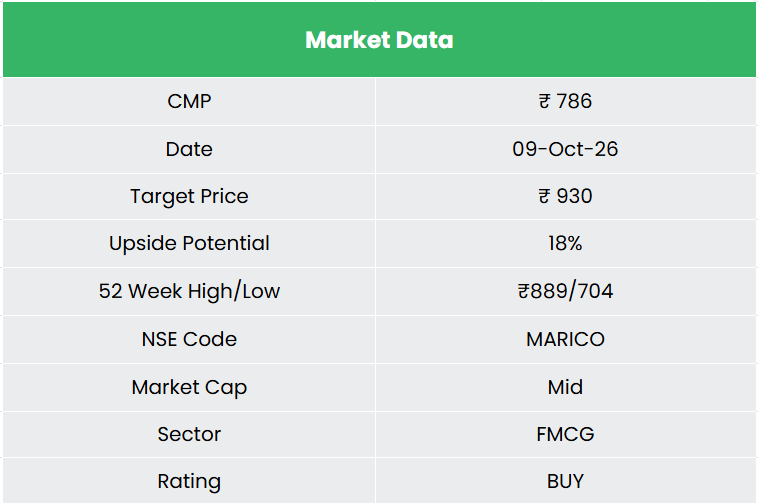
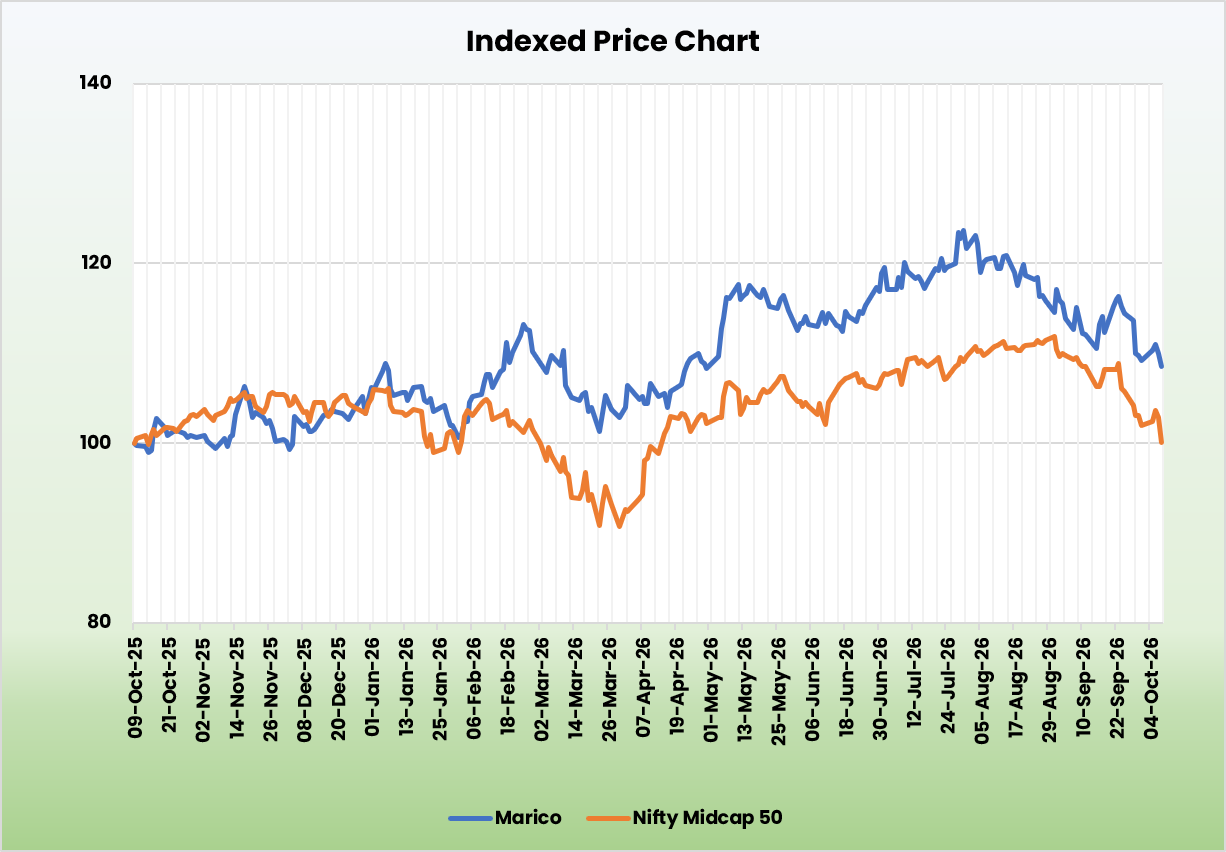
We believe Marico presents a compelling investment opportunity, driven by its strategic focus on strengthening distribution channels and its track record of consistent volume growth. We recommend a BUY rating in the stock with the target price (TP) of Rs.930, 46x FY28E EPS. We also encourage maintaining a stop-loss at 20% from the entry price to manage potential downside risk effectively.
SWOT Analysis
| Strength | Weakness |
|
|
| Opportunities | Threats |
|
|
Disclaimer: Investments in the securities market are subject to market risks, read all related documents carefully before investing. Securities quoted here are exemplary, not recommendatory. Please consult your financial advisor before investing. Please note that we do not guarantee any assured returns for the securities quoted here.
Research disclaimer: Investment in the securities market is subject to market risks. Read all the related documents carefully before investing. Registration granted by SEBI, and certification from NISM in no way guarantee the performance of the intermediary or provide any assurance of returns to investors.
For more details, please read the disclaimer.